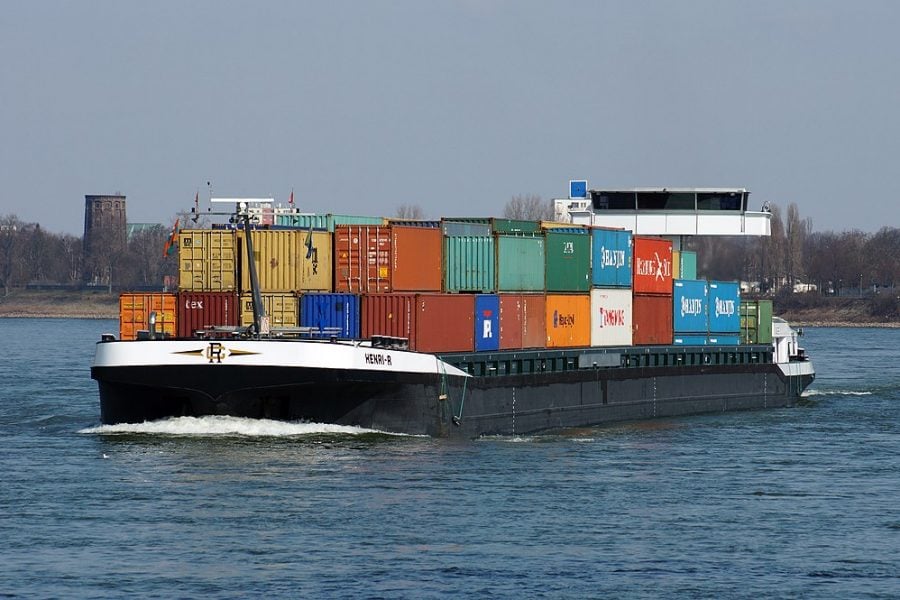
The termination of the Moroccan pipeline Gas-Maghreb-Europe (GME) agreement has reportedly raised the weight of gas per ship to almost 70%, according to the latest statistical bulletin of the pipeline’s managing company, Enagás.
Gas by pipe has dropped from 52% to 31% in December, leading Spain to record losses of 6,236 GWh from the Maghreb and Medgaz agreement fallout.
Liquefied natural gas (LNG) that entered the Spanish market last December accounted for almost 70% of the total, compared to 52.4% in the same month of 2020.
In contrast, natural gas (NG), neither liquefied nor regasified, transported by pipeline, accounted for 31.2% last December, compared to 52.4% in the same month of 2020.
Enagás data reveal the Maghreb that while in December 2020, the inflow of gas through Tarifa reached 6,236 GWh, in December of this year it was zero.
A flow that was only partly compensated by Medgaz, the pipeline that directly links Algeria with Spain, through Almeria, only covered 23% of the gas demand in Spain last month.
The supply amounted to a mere 8,260 GWh in December 2021, compared to 6,695 GWh in the same month of 2020.
Just 1,565 GWh difference. Since this month, Medgaz’s capacity has increased from 8 billion cubic meters (bcm) of gas to 10 bcm.
According to Enagás data, demand for natural gas in the domestic market last year increased by 5.1%, to 378,500 GWh. Conventional demand rose by 6.2% and gas for electricity production by 1.6%.
Spanish Vice-President for Ecological Transition, Teresa Ribera, and the Minister of Foreign Affairs, José Manuel Albares, deployed a media campaign to counter rampant fears of a possible shortage.
Algeria has since attempted to compensate by ship the gas lost through Tarifa. The result is that, compared to the 495 GWh of LNG that Sonatrach shipped to Spain in December 2020, this volume rose to 2,357 GWh last month.
Algeria remains Spain’s main gas supplier, with a demand coverage of 42%. The United States supplies up 14.4% of Spanish gas demand, ahead of Nigeria, which has moved up to third place, with 11.4%.
Russia has also climbed up the ranking, with 8.7%. These variations in LNG suppliers could also be explained by the closure of the Maghreb.
Gas through Morocco stopped flowing on October 31, following the termination of the supply contract between Algerian Sonatrach and Spanish Naturgy, as well as that between Naturgy and Morocco for the operation and maintenance of the 500 km pipeline on Moroccan soil.
Both contracts, which had been in force for 25 years, expired on the same day. The renewal attempts by the Spanish energy company, which had been negotiating with both countries for two years, were unsuccessful.
Algeria has shown it is perfectly able to quench Spain’s demand without the Moroccan passage, but the fact that the gas via ship needs to be liquefied on the coasts of origin and regasified at its destination makes it more expensive than natural gas.
Its price is subject to the fluctuations of international markets and the freight rates of methane tankers, meaning that the shorter the distance, the lower the price.




add your comment
Terms of publication : Not to offend the writer, people, sacred things, or attack religions or the divine self, and refrain from racist incitement and insults.