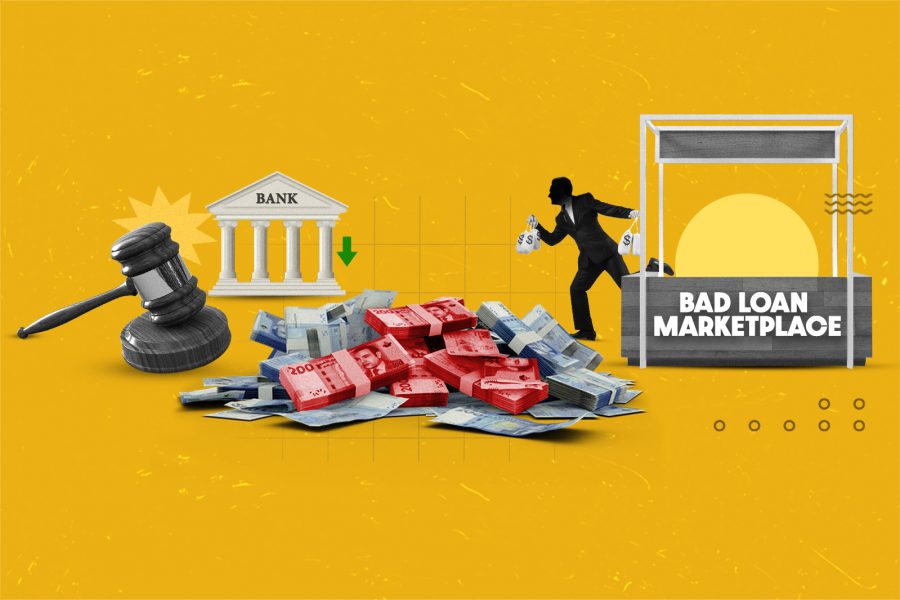
Unpaid debts, or non-performing loans (NPLs), are surging in Morocco, squeezing bank profits and stability. Economists like Mohamed Jedri point to potential causes like poor company management or businesses struggling financially.
‘These unpaid loans are a problem for banks. They would normally go to court to get the money back, but this is a long and expensive process,’ Jedri told Hespress EN.
Non-performing loans in Morocco have fluctuated over time. In March 2002, they were at their lowest level, recorded at $2.85 billion USD. However, by July 2021, they had risen significantly to $10.56 billion USD, the highest level recorded.
To tackle this, Morocco is exploring a novel marketplace where banks can sell these NPLs.
“The new marketplace where banks can sell these unpaid loans, would allow banks to avoid going to court. The loans would be sold for less than their original value and would include loans given to individuals and businesses,” said Jedri.
The economist says this new marketplace will be difficult to set up in Morocco. Traditionally, the relationship between a bank and its client is confidential and based on trust. Laws would need to be changed to allow banks to sell unpaid loans.
Jedri clarified that if this loan marketplace isn't created, companies with unpaid loans could face having their assets seized by the bank, rather than going through bankruptcy.
According to Bank Al-Maghrib, NPLs reached MAD 94.1 billion (approximately $9.9 billion) at the end of January 2024, representing 8.8% of total outstanding bank loans. While the value of non-performing loans held by households increased to MAD 38.7 billion.
To address the NPL problem, Morocco has been working on establishing a secondary market for unpaid debts.
This market would allow banks to sell their NPLs to local or international investors, who could then attempt to collect the debts or restructure them to make them more repayable.
The creation of a secondary market for unpaid debts (NPLs) in Morocco is moving forward. However, establishing a functional market requires addressing several key challenges.
One major hurdle is crafting a clear legal and regulatory framework. This framework needs to govern the sale and purchase of NPLs in a way that protects all parties involved.
A crucial aspect of this is ensuring data protection. Customer data, such as names, addresses, and financial information, needs robust safeguards throughout the NPL transfer process.
The new law must align with Moroccan data privacy regulations. This means ensuring the secure storage and handling of customer information by banks, investors, and any other parties involved in the NPL transaction.
Another challenge lies in managing the potential increase in costs for borrowers. When NPLs are sold, there's a risk that additional fees or penalties might be added to the debt.
This could further strain borrowers who are already struggling to repay their loans. The new regulations must consider measures to mitigate these cost increases and ensure fairness for borrowers throughout the NPL sale process.
Despite these challenges, there's a positive movement towards establishing this market. Bank Al-Maghrib prepared a draft law allowing banks to sell NPLs to third-party investors.
This represents a significant step forward. Bank Al-Maghrib has been actively collaborating with stakeholders like banks, financial institutions, and the International Finance Corporation (IFC) to address sensitive issues.
These collaborations are crucial for tackling issues like data protection and contract validity and determining appropriate fees associated with NPL transactions.
An inter-ministerial committee led by Bank Al-Maghrib has finalized the draft law, which involved relevant ministries such as finance, justice, and industry.
This collaborative effort ensures a comprehensive approach to the legal and regulatory framework for the secondary market. With an anticipated implementation in 2024, establishing this market is on track.
The potential benefits of a secondary market for NPLs are significant. Banks could reduce their risk exposure by selling off these non-performing loans, which would improve their overall financial health.
Investors with expertise in debt collection may be able to recover more money from these debts than banks can on their own.
Ultimately, a healthier banking sector with lower NPL burdens would contribute to greater financial stability for the Moroccan economy.
A key point of contention in creating this market is who buys these NPLs. Major Moroccan banks are lobbying to restrict licenses for purchasing NPLs to domestically licensed credit institutions and companies. Their argument centers around protecting their competitive advantage in the market.
However, others believe this approach is short-sighted. Opening the market to foreign investors could bring invaluable expertise in debt collection and potentially more capital, ultimately leading to a more efficient and successful NPL market.
Legal issues are another layer of complexity. Concerns have been raised regarding the legality of banks selling NPLs to investors, specifically citing Article 192 of the Moroccan Code of Obligations and Contracts.
This article states that transferring a disputed right, such as a debt, whose validity is in question is null and void unless the debtor consents to the transfer.
This could pose significant challenges if there are existing legal disputes surrounding the debt. Legal experts are working to address these concerns and ensure a clear legal framework for NPL transactions.
Tax implications add another wrinkle to the equation. The General Directorate of Taxation is expressing concerns about the tax treatment of NPL transfers. Specifically, they are unsure about the legitimacy of doubtful debts (debts with very low recovery prospects) being sold on the secondary market.
Additionally, they scrutinize the practice of banks claiming tax deductions for NPLs declared as inventory. They fear this could be exploited for tax evasion purposes.
Beyond legal and financial hurdles, practical challenges also exist. Morocco's current lack of a clear legal framework for debt collection makes it difficult for banks to recover NPLs, especially those tied to real estate assets.
The Moroccan real estate market is experiencing a slowdown, making selling these assets and recoup the debt even harder.
The ever-growing volume of NPLs, now at a staggering MAD 95.4 billion, further highlights the urgency of establishing a well-defined secondary market. This market could provide a much-needed avenue for banks to offload these problematic debts and improve their overall financial health.
Despite these challenges, the Moroccan authorities, led by Bank Al-Maghrib, remain committed to establishing a secondary market for NPLs.
The potential benefits are significant. By selling their NPLs, banks could reduce risk exposure and improve their balance sheets. Investors with expertise in debt collection may be able to recover more money from these debts than banks can on their own.
Ultimately, a healthier banking sector with lower NPLs would contribute to greater financial stability for the Moroccan economy.
Navigating these legal, tax, and operational hurdles successfully is crucial for creating a well-functioning secondary market that can deliver these benefits and have a positive impact on Morocco's financial system and broader economy.





add your comment
Terms of publication : Not to offend the writer, people, sacred things, or attack religions or the divine self, and refrain from racist incitement and insults.